Dave: Credit, Cash & Money App
Dave Operating LLCFinanceVerified
- 228.50K Reviews
- 4.6
- Downloads
- 10,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
When an unexpected expense lands between paydays, I want to know two things quickly: what help is available, and what will happen to my next paycheck if I use it. That is the practical question I bring to Dave: Credit, Cash & Money App. It is a finance app from Dave Operating LLC, built around short-term cash access alongside tools for managing money, finding work, and earning interest. I see its best use as a way to handle a temporary squeeze while keeping an eye on what comes next—not as a replacement for a budget or a long-term plan.
A shortfall is a timing problem, not a plan
Picture a routine week: rent and a utility bill are due, but a paycheck is still a few days away. A small expense can then cause a chain reaction, from a low balance to a missed payment. In that moment, an app that brings cash options and everyday money tools into one place can be useful. Dave’s store summary says eligible users can get up to $500, but I would treat that as a ceiling rather than an amount everyone should expect. The right question is whether the option shown to you fits the size of your actual gap.
That distinction matters because a cash advance does not make the expense disappear. It changes when money is available and when repayment is due, so the next pay cycle deserves as much attention as the immediate need. I would first write down the bill, the due date, and the paycheck date, then decide whether a shortfall is temporary or part of a recurring pattern. If the same gap appears every month, an advance may buy time without solving the underlying mismatch.
Following the flow from setup to a decision
Getting started means creating an account and linking a bank account, as the published review experience describes. That connection is the handoff between Dave’s tools and your everyday finances: the app can only be useful if the information it works with reflects your real situation. Before relying on any displayed balance or upcoming expense, I would check that the linked account is the one where income arrives and regular bills are paid. If your money is spread across several accounts, a partial picture can make a decision look safer than it is.
Once inside, I would use the budgeting view as a prompt to inspect spending, not as a substitute for checking my own bank activity. The original experience found that the tool could track expenses, flag likely upcoming bills, and send nudges when spending was approaching a limit. Those are helpful cues, especially when I am busy and a bill tends to slip my mind. They are still cues: I would verify a predicted bill and its date before planning around it, since an estimate is not the same thing as a confirmed payment schedule.
For a concrete routine, imagine I have a modest car expense before payday. I would compare the amount due with the cash I already have, look at what bills are due before the next income arrives, and only then consider an advance. If I use one, I would note the repayment timing alongside those bills and avoid treating the available amount as extra spending money. That small step is the difference between covering a one-off need and accidentally making the following week tighter.
How the tools fit together in everyday use
Dave brings several kinds of help under one roof, but they solve different problems. Cash access addresses an immediate timing gap; budgeting helps make spending more visible; credit-building is aimed at longer-term credit history; and work suggestions may help someone look for additional income. I would not judge all of these by one measure. The useful question is which part addresses the reason you opened the app in the first place, and whether you can follow through on its next step.
Other Stories to Read




Features That Stand Out
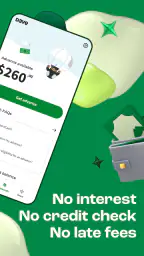
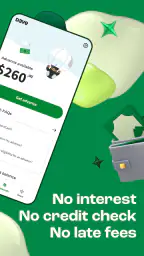
Alright, let’s dive into some of the features that really stood out to me. One of the headliners of the app is its ability to give you a cash advance of up to $500 without any interest. Yeah, you heard that right—no interest. It’s like borrowing from a friend who doesn’t charge you to pay them back. You can repay it on your next payday. This feature is a lifesaver when you’re caught in a pinch.
Even when an advance is the right choice, I would keep the decision deliberately boring: borrow only what covers the immediate need, check the repayment date, and leave enough room for essentials afterward. That is more useful than focusing on the maximum. The offer may not be the same for every person or situation, so I would review the terms and repayment details presented in the app before confirming anything. “No interest” should not be read as a promise that every possible service or transaction is cost-free; the app’s broader promise is no hidden fees, and I would still read what applies to the action I am taking.
Another cool feature is the budgeting tool. It’s pretty intuitive and helps you keep track of your expenses. It even predicts upcoming bills based on your spending habits. It’s like having a personal financial advisor right in your pocket. I love how it sends gentle nudges if you’re about to overspend. My favorite part? The app’s budgeting tool doesn’t make you feel guilty about your spending habits—it’s more like a friendly guide.
One practical way to get more from that view is to check it at two different moments: before a known bill is due and shortly after income arrives. The first check can help catch a tight week early; the second can show whether the plan survived contact with actual spending. If something looks off, I would compare it with the bank account rather than immediately changing my budget around an estimate. This makes the tool a useful early-warning system without asking it to be a perfect ledger.
Credit and extra income serve different timelines
If you’re looking to build or improve your credit score, Dave has a neat feature for that too. It offers a credit-building service that reports your payments to major credit bureaus. It’s a straightforward way to give your credit score a little boost without diving into complicated credit card games.
I would think of that as a separate, longer-term track from a cash advance. Someone focused on building credit should look carefully at how the service works and what commitments it involves, then decide whether it fits alongside existing credit accounts. It is not an instant fix for a credit problem, and anyone who already has a reliable credit-building routine may find less reason to add another one. The appeal is simplicity; the trade-off is that a simple tool still needs regular, on-time follow-through to be worthwhile.
Plus, the app includes a side hustle feature that suggests part-time job opportunities based on your skills and location. It’s a nice touch for those who want to earn a bit more cash on the side.
This is a different kind of handoff: the app can point you toward opportunities, but the work, application, and income are up to you. I would use the suggestions as a starting point for a focused search, not assume that a listing means a job is secured or that earnings will arrive in time for an urgent bill. If the problem is a persistent monthly deficit, looking for extra income may be more durable than repeatedly shifting money forward, though it takes longer and may not suit everyone’s schedule.
Where the experience can snag
The main friction is that several tools can create a feeling of control before the underlying cash flow is actually comfortable. A spending reminder can help me pause, but it cannot reduce a bill; a cash advance can bridge a gap, but repayment puts pressure on a later date. I would be cautious about using the advance option for recurring expenses or discretionary purchases. If the next paycheck is already assigned to rent, food, and transport, moving part of it earlier could simply relocate the stress.
There is also a practical dependency in linking financial activity to an app: the information needs to be current and the account needs to reflect the money you intend to manage. I would check the figures against my bank before making a consequential decision, especially if I recently changed where income is deposited or where bills are paid. That extra check is not a criticism of Dave alone; it is sensible whenever an app’s view becomes part of a borrowing decision.
Dave is not the right fit for everyone. If you already have a low-cost, dependable source of emergency savings, using that may be simpler than taking an advance and planning around repayment. If your top priority is detailed household accounting, shared budgets, or a broad investment picture, a dedicated tool designed around those tasks may suit you better. Dave’s strength is bringing short-term cash help together with a few adjacent money and work features, not being every kind of financial service at once.
Support, security, and the trust question
Now, onto something that often gets overlooked—customer support. Dave’s team is pretty responsive, and they’re available through chat, which is super convenient. I had a minor issue setting up my account, and they sorted it out in no time.
When money is involved, I would use in-app support for account-specific questions rather than guessing from a general explanation, especially if I need help understanding a transaction or a repayment. It is also worth keeping a record of what you agreed to and checking your bank activity afterward. Support can help untangle a problem, but careful review before and after a money movement is still part of using the app responsibly.
As for security, the app uses bank-level encryption to protect your information. I felt pretty confident knowing my data was safe, which is a huge relief considering how many apps there are out there that don’t take security seriously.
That reassurance is useful, but I still treat any finance app as something that deserves basic account hygiene: use a strong, unique password and be attentive to account alerts. Security measures reduce risk; they do not make careless account access harmless. For me, the sensible approach is to use the convenience while remaining aware of which bank account is connected and where I would go for help if something looked wrong.
Who is most likely to benefit
Dave makes the most sense for someone whose income is reasonably predictable but whose expenses sometimes land awkwardly between paydays, and who wants a quick view of spending alongside possible cash support. It can also appeal to a person who prefers having credit-building and job-search prompts close to the same financial dashboard. The app is free to download, has an Everyone content rating, and is rated 4.6 on average from around 587,000 ratings; that broad response is encouraging, though it cannot tell me whether the tools match an individual’s needs.
Someone with irregular income should be especially deliberate. A repayment tied to an expected payday can be harder to plan around when the amount or date changes. I would map out a conservative version of the next few weeks before taking an advance, using the earliest plausible income date rather than the most optimistic one. If the numbers only work when every payment arrives exactly on time, I would look for another option or contact the biller about timing instead.
The app has passed 10 million installs, and its current version is 3.93.1; it supports devices running version 9 or later. Dave first arrived on April 24, 2017, so it is an established product rather than a brand-new finance experiment. Those details offer context, but my recommendation still comes down to fit: I would try it for the tools I actually need, not install it simply because it is popular.
Overall Experience
Using the Dave: Credit, Cash & Money App has been a pretty smooth ride. For anyone needing a handy tool to manage finances and occasionally get an advance, it’s worth checking out. Sure, it’s not a substitute for financial planning, but it’s a great companion that helps you stay afloat between paychecks.
So, if you find yourself in a situation where you need a little financial wiggle room, or you just want to keep better track of your expenses, give Dave a shot. It’s like having a financial buddy who’s got your back without all the complicated jargon.
My recommendation comes with one simple condition: use the app to make the next decision clearer, not to avoid making one. Before accepting an advance, confirm the amount, the repayment timing, and the bills that will follow; before relying on a predicted expense, check it against your account. If you want a practical bridge and can plan for the handoff back to your next paycheck, Dave can be useful. If you need a lasting fix for bills that exceed income, a bridge alone is not enough.
Highlights
- No hidden fees or interest charges.
- Instant cash advances available.
- User-friendly interface.
- Helps avoid overdraft fees.
- Automatic budgeting tools.
Limitations
- Limited to $500 cash advances.
- Requires bank account access.
- No support for all banks.
- No investment options.
- Limited financial insights.
Frequently Asked Questions
01What features does the Dave app offer?
Dave offers a range of financial services including paycheck advances, budgeting tools, and an automatic savings feature. The app also provides users with a side hustle feature to find gig work, and is designed to help users avoid overdraft fees by predicting upcoming expenses and providing notifications.
02Is the Dave app safe to use for my financial transactions?
Yes, Dave employs bank-level security measures to protect your financial data. The app uses encryption and secure servers to ensure that your information is safe. Additionally, Dave is partnered with banking institutions that are FDIC-insured, offering an extra layer of security for your transactions.
03How does the paycheck advance feature work in the Dave app?
The paycheck advance feature allows users to access a portion of their upcoming paycheck before payday. Users can request up to $100 in advance without any interest. Repayment is automatically scheduled for your next payday, and there are no hidden fees, making it a convenient option for managing cash flow.
04What are the costs associated with using the Dave app?
Dave charges a monthly subscription fee of $1, which provides access to its full range of features. While there are no fees for paycheck advances, users have the option to provide a voluntary tip. This tip helps support the service and is completely optional, ensuring transparency and affordability.
05Can I use the Dave app if I have a poor credit history?
Yes, Dave does not require a credit check to use its services. The app is designed to assist users in managing their finances and avoiding overdraft fees, regardless of their credit history. This makes it accessible to a broader range of users looking to improve their financial situation.


